
Unsure about estate planning? Learn why it’s crucial and what you need to know to protect your loved ones and assets. This comprehensive guide breaks down the essentials.
Introduction
Let’s face it, talking about what happens after we’re gone isn’t exactly top of mind for most of us. It’s a bit morbid, isn’t it? We’re busy living our lives, building careers, raising families, and enjoying the fruits of our labor. The idea of planning for the end can feel overwhelming, like staring at a mountain you’re not sure you can climb. But here’s the kicker: not having a plan in place can leave your loved ones in a far more difficult and stressful situation than you can imagine. That’s where the importance of estate planning—what you need to know truly shines. It’s not about dwelling on the negative; it’s about taking control, making smart decisions, and ensuring your legacy is protected. Think of it as a final act of love and responsibility, a way to say, “I’ve got this covered, even when I’m not here.”
What Exactly Is Estate Planning, Anyway?
Before we dive headfirst into why it’s so important, let’s get on the same page about what we’re actually talking about. Estate planning isn’t just for the super-wealthy or those on their last legs. It’s a comprehensive process of setting up a plan for how your assets will be managed and distributed during your lifetime and after your death. This involves anticipating and arranging for the management of your affairs should you become incapacitated, and the orderly settlement of your estate after you pass on. It’s a roadmap for your financial and personal wishes, designed to minimize confusion, reduce potential conflicts among beneficiaries, and ensure your assets go where you want them to, when you want them to, and in the way you want them to.
Beyond the Basics: More Than Just a Will
Many people mistakenly believe that a will is the be-all and end-all of estate planning. While a will is undoubtedly a cornerstone, it’s just one piece of a much larger puzzle. A comprehensive estate plan can encompass a variety of legal documents and strategies, each serving a specific purpose.
- Wills: This is your primary document that dictates how your property will be distributed after your death. It also names an executor to carry out your wishes and can appoint guardians for minor children.
- Trusts: These are legal arrangements where a trustee holds and manages assets for the benefit of beneficiaries. Trusts can offer significant advantages, such as avoiding probate, providing for beneficiaries with special needs, and minimizing estate taxes.
- Powers of Attorney: These documents appoint someone to make financial or healthcare decisions on your behalf if you become unable to do so yourself. This is crucial for managing your affairs while you’re still alive but incapacitated.
- Advance Healthcare Directives (Living Wills): These express your wishes regarding medical treatment and end-of-life care, ensuring your healthcare providers and loved ones know your preferences.
- Beneficiary Designations: For certain assets like life insurance policies, retirement accounts (401(k)s, IRAs), and payable-on-death accounts, you can directly name beneficiaries. These designations often supersede what’s written in your will, so keeping them up-to-date is vital.
Why is Estate Planning So Crucial? Let’s Break It Down.
Okay, so now we know what it is. But why should you be losing sleep over it? Well, for starters, it’s about peace of mind. Knowing that you’ve taken steps to protect your loved ones and your assets can be incredibly liberating. But there’s more to it than just feeling good.
Protecting Your Loved Ones

This is, hands down, the most compelling reason for estate planning. Imagine the grief your family will already be experiencing after your passing. Do you really want to add to their burden by leaving them with a complicated, potentially contentious, and costly process of figuring out your affairs? Without a plan, your assets could be tied up in probate for months, or even years, leaving your beneficiaries with little to no financial support during that time. Furthermore, without clear instructions, your loved ones might disagree on how your assets should be distributed, leading to bitter disputes that can fracture family relationships forever.
Think about your children, your spouse, or other dependents. Who will take care of them? If you have minor children, a will is absolutely essential for naming a guardian. Without this designation, a court will decide who raises your children, and that decision might not align with your values or wishes at all.
Minimizing Estate Taxes and Other Costs
While the thought of paying taxes on your hard-earned money after you’re gone might seem unfair, it’s a reality for many. However, a well-crafted estate plan can help minimize estate taxes, capital gains taxes, and other liabilities. By utilizing strategies like trusts, gifts, and specific investment vehicles, you can significantly reduce the tax burden on your estate, leaving more for your beneficiaries. Beyond taxes, there are also administrative costs associated with settling an estate, such as probate fees, legal expenses, and appraisal costs. A good estate plan can help streamline these processes, reducing the overall cost and ensuring more of your assets reach your intended recipients.
Avoiding the Probate Maze
Probate is the legal process of validating a will and distributing an estate. It can be a lengthy, expensive, and public affair. Court proceedings, legal fees, and administrative hurdles can add up quickly. For smaller estates, the cost and time involved in probate might outweigh the benefit. For larger estates, it can be a significant drain on resources. Certain estate planning tools, like revocable living trusts, can help bypass the probate process altogether, allowing for a much faster and more private transfer of assets to your beneficiaries. It’s a way to keep your affairs out of the public eye and get things done more efficiently.
Ensuring Your Wishes Are Heard
This is the heart of it all, isn’t it? You’ve worked hard to build a life, to accumulate assets, and to make choices that reflect your values. Estate planning is your opportunity to ensure those choices continue to be honored even after you’re no longer able to voice them. Whether it’s deciding who gets your prized vintage car, ensuring a specific charity receives a donation, or outlining your preferences for medical care, your estate plan is your voice for the future. Without it, your wishes could be misinterpreted, ignored, or simply unknown.
The Importance of Estate Planning—What You Need To Know
for Different Life Stages
The “right” estate plan isn’t a one-size-fits-all solution. It evolves as your life does. What might be appropriate for a single young professional will likely differ from the needs of a married couple with young children, or a retiree with a substantial portfolio.
Young Adults and Singles: Laying the Foundation
Even if you don’t have a lot of assets yet, estate planning is still a good idea. It’s about establishing basic protections.
- Basic Will: Essential for naming an executor and specifying how any property you do have will be distributed.
- Healthcare Directive and Power of Attorney: Crucial for designating someone to make medical and financial decisions if you’re incapacitated, especially if your parents or other loved ones might not automatically have that right depending on your location and age.
- Beneficiary Designations: Ensure your bank accounts and any small insurance policies are updated.
Couples and Families with Children: Protecting Your Unit
Once you have a family, the stakes get higher.
- Guardianship: Naming guardians for your minor children is paramount. This is often the most emotionally charged decision for parents.
- Living Trusts: Can help avoid probate for your primary residence and other significant assets, ensuring faster financial support for your surviving spouse and children.
- Life Insurance: Consider adequate life insurance to provide for your family’s ongoing needs if a breadwinner passes away.
- Contingent Beneficiaries: Designate secondary beneficiaries for your accounts and policies in case your primary beneficiary predeceases you.
Mid-Career Professionals and Business Owners: Building and Preserving
As your career progresses and you potentially build a business, your estate becomes more complex.
- Business Succession Planning: If you own a business, you need a plan for its continuation or sale upon your death or incapacity. This is vital for your employees and your family’s financial security.
- Tax Planning: With a larger estate, minimizing estate taxes becomes a more significant consideration.
- Trusts for Asset Protection: Consider trusts that can protect assets from potential creditors or lawsuits.
Retirees and Seniors: Securing Your Legacy
For those entering or in retirement, the focus shifts towards ensuring comfortable retirement living and the smooth transfer of wealth.
- Review and Update: Your existing plan may need adjustments based on changes in your assets, family dynamics, or tax laws.
- Long-Term Care Provisions: Consider how you’ll cover potential long-term care costs.
- Charitable Giving: If philanthropy is important to you, incorporate it into your estate plan.
- Simplified Distribution: Focus on making the distribution of assets as straightforward as possible for your beneficiaries.
FAQs About Estate Planning
Got more questions? It’s totally understandable. Here are some common ones that pop up:
Q: How much does estate planning cost?
A: The cost varies widely depending on the complexity of your estate, the attorney you choose, and the documents required. A simple will might cost a few hundred dollars, while a complex trust setup could run into thousands. It’s an investment, though, and often saves far more in the long run.
Q: How often should I update my estate plan?
A: You should review and update your estate plan every three to five years, or whenever significant life events occur. Major life events include marriage, divorce, the birth or adoption of a child, the death of a beneficiary or executor, a significant change in your financial situation, or moving to a new state.
Q: What happens if I don’t have an estate plan?
A: If you die without a will (intestate), the state’s laws will determine how your assets are distributed. This often means your assets go to your closest relatives, but not necessarily in proportions you would have chosen, and it can be a lengthy and public process. Guardianship for minor children will also be decided by a court.
Q: Can I do estate planning myself?
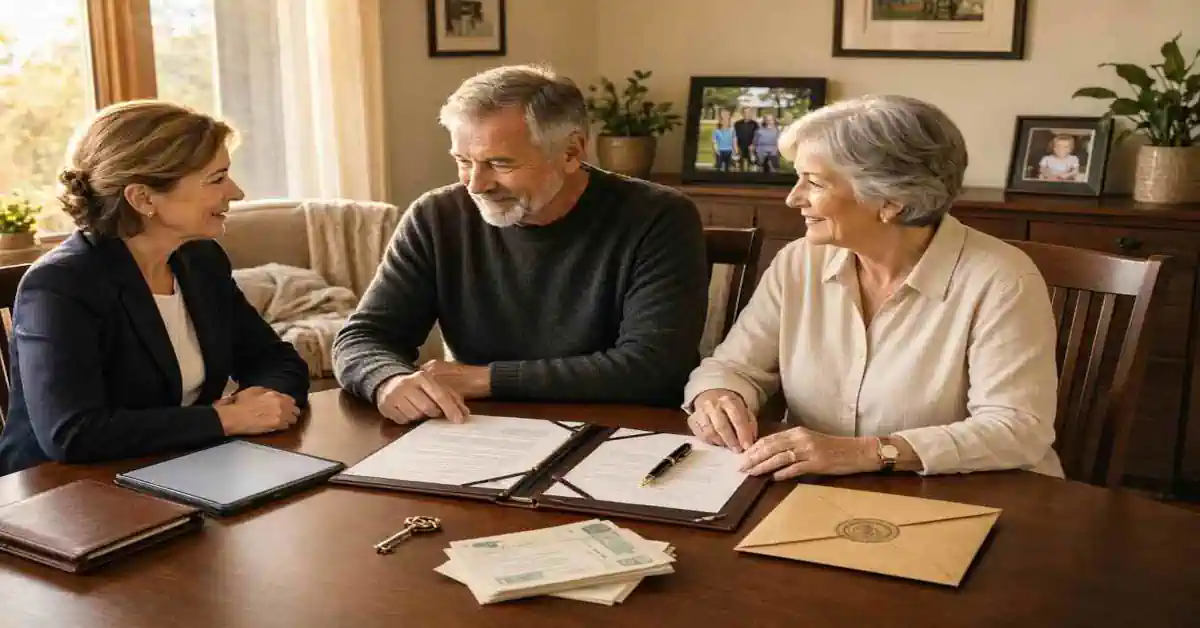
A: While DIY options exist, especially for simple wills, it’s generally recommended to work with an experienced estate planning attorney. They can ensure your documents are legally sound, reflect your specific wishes, and are tailored to your unique situation, avoiding potential pitfalls that could invalidate your plan.
Q: What is the difference between an executor and a trustee?
A: An executor is appointed in a will to manage the distribution of assets after death, typically through the probate process. A trustee manages assets held within a trust, either during your lifetime or after your death, according to the terms of the trust agreement.
Getting Started: Taking the First Step
The most important thing is to get started. Don’t let the perceived complexity paralyze you. Here’s how to approach it:
- Make a List: Jot down all your assets (real estate, bank accounts, investments, valuable possessions) and your liabilities (debts, mortgages). Also, list your beneficiaries and potential guardians for any minor children.
- Consider Your Wishes: Think about who you want to inherit what, who should manage your affairs if you become incapacitated, and your healthcare preferences.
- Research Attorneys: Look for estate planning attorneys in your area. Ask for recommendations, check reviews, and schedule initial consultations to find someone you feel comfortable with.
- Be Open and Honest: During your meetings with your attorney, be clear and honest about your assets, your family situation, and your desires. The more information they have, the better they can advise you.
- Review and Sign: Once your documents are drafted, review them carefully. Ensure they accurately reflect your wishes. Then, sign them according to legal requirements.
- Store Safely and Inform: Keep your original documents in a secure place (like a safe deposit box or with your attorney) and inform your executor and trusted family members where they are located.
Conclusion
The importance of estate planning—what you need to know boils down to this: it’s about foresight, responsibility, and a profound act of care for those you leave behind. It’s an investment in your peace of mind today and in the well-being of your loved ones tomorrow. While the topic might seem daunting, breaking it down into manageable steps and seeking professional guidance can make the process much less intimidating. Don’t wait for a crisis to strike. Take control of your legacy, protect your family, and ensure your final wishes are honored. Your future self, and your loved ones, will thank you for it.
Disclaimer: This article is for informational and educational purposes only and should not be construed as financial, investment, or legal advice. Financial markets and product terms change frequently. Always conduct your own research or consult with a qualified financial advisor before making any financial decisions.